Combine FHA Financing With a New, Fully Owned Solar System
Eligible homebuyers and homeowners may be able to combine FHA financing with a brand-new solar installation while receiving separately funded taxable earned-income compensation equal to 3.5% of the applicable property value, up to $13,000, subject to FHA, lender, property, solar-provider, and program requirements.
Eligibility, loan approval, compensation, property qualification, solar installation, and program availability are subject to applicable requirements. This is not a commitment to lend.
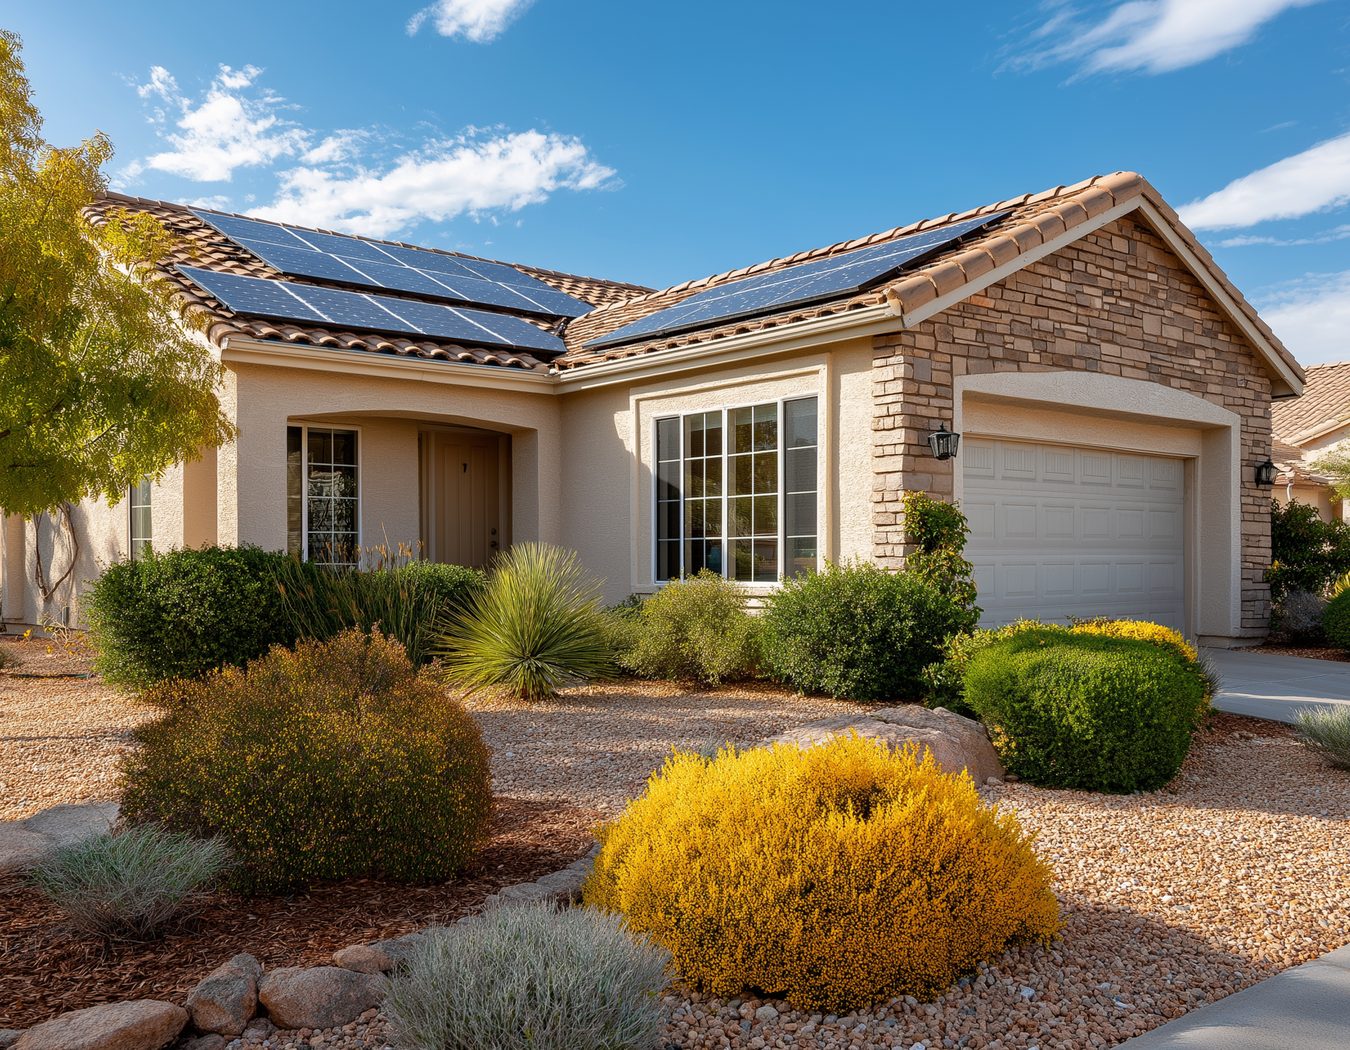
One FHA Mortgage. A New Solar Installation. No Separate Solar Loan.
Eligible borrowers may be able to finance an approved new solar installation as part of an FHA purchase or eligible FHA rate-and-term refinance — subject to applicable requirements.
Fully Owned Solar
The program is designed for a new solar system that the homeowner owns rather than a solar lease or power-purchase agreement.
No Separate Solar Loan
Eligible solar costs may be incorporated into the FHA financing, subject to applicable requirements.
No Separate Second Mortgage
The program does not create a traditional second mortgage for the solar installation.
Purchase and Refinance Options
The structure may be available for an eligible FHA home purchase or qualifying FHA rate-and-term refinance.
Potential Taxable Earned-Income Compensation
Eligible borrowers may receive separately funded taxable earned-income compensation equal to 3.5% of the applicable property value, up to $13,000, subject to program requirements.
- Is not borrowed from the homeowner's equity
- Is not part of the mortgage proceeds
- Is not a traditional down-payment-assistance second mortgage
- Does not require repayment under the stated program structure
- Is treated as taxable earned income
- May be subject to restrictions on how or when it becomes available
- Is not guaranteed
Potential approved uses may include:
FHA Solar Financing for a Home Purchase
Eligible homebuyers may be able to purchase a primary residence using FHA financing and include an approved new solar installation in the transaction.
-
One combined financing structureCombine the home purchase and eligible solar cost into a single FHA financing structure.
-
Avoid a separate consumer solar loanEligible solar costs may be incorporated into your FHA loan rather than a separate loan or lease.
-
A fully owned solar installationMove in with a new solar system that you own from day one.
-
Review potential compensationExplore whether potential compensation may help with approved transaction needs.
-
Coordinated processRobert helps coordinate the mortgage, appraisal, closing, and solar-installation process from start to finish.
See what a purchase transaction could look like
Answer a few short questions and we'll follow up with a personalized purchase review.
Review My Purchase OptionsFHA Solar Rate-and-Term Refinance
Eligible homeowners may be able to combine a qualifying FHA rate-and-term refinance with a new solar installation.
-
Not a cash-out refinanceThis is not the FHA cash-out refinance option described elsewhere on this website.
-
Must satisfy FHA and lender requirementsThe refinance must meet applicable FHA and lender guidelines to move forward.
-
Net tangible benefit requiredAny required FHA net tangible benefit must be established for the transaction.
-
Existing solar may affect eligibilityExisting owned, financed, or leased solar may affect eligibility for this program.
-
Multiple factors reviewedApproval depends on the borrower, property, current mortgage, appraisal, and program requirements.
Find out if your refinance may qualify
Share a few details about your current mortgage and we'll follow up with a personalized refinance review.
Review My Refinance OptionsYou May Be Eligible If…
This is a general overview. A personalized review will confirm your actual eligibility.
The transaction is an eligible FHA purchase or FHA rate-and-term refinance.
The property is or will be the borrower's primary residence.
The property is eligible for a new solar installation.
The home does not currently have an owned, financed, or leased solar system.
The borrower satisfies applicable FHA and lender credit, income, asset, occupancy, and repayment requirements.
The property satisfies FHA appraisal and condition requirements.
The solar system and provider satisfy program requirements.
The transaction is located in an eligible state.
The solar installation is completed within the required period after closing.
A minimum qualifying credit score may apply. Your personalized review will confirm the requirements that apply to your specific lender and transaction.
Situations That May Not Qualify
Condominiums are currently not eligible under this program.
Properties with an existing owned solar system may not qualify.
Properties with an existing leased solar system may not qualify.
Properties with an existing financed solar obligation may not qualify.
Transactions intended to refinance or replace an existing solar obligation.
Second homes are not eligible.
Investment properties are not eligible.
FHA cash-out refinances are not part of this program.
Properties that cannot legally or physically accommodate the proposed solar system.
Transactions in states where the program or mortgage services are unavailable.
How the FHA Solar Program Works
A step-by-step look at what to expect from your first questionnaire to a completed solar installation.
- 1
Complete the Eligibility Questionnaire
Tell us whether you are purchasing or refinancing and provide basic property information.
- 2
Review FHA Qualification
Review credit, income, assets, occupancy, current mortgage, and transaction goals.
- 3
Confirm Property and Program Eligibility
Determine whether the property and proposed transaction satisfy current program requirements.
- 4
Review the Solar Proposal
An approved solar provider prepares the system design, installation plan, and cost proposal.
- 5
Complete the FHA Loan Process
Complete appraisal, underwriting, title review, loan conditions, and final approval.
- 6
Close the Mortgage Transaction
Close the approved purchase or refinance with the eligible solar amount incorporated into the financing.
- 7
Install and Inspect the Solar System
Complete the installation, final inspection, and remaining escrow disbursement according to program requirements.
FHA Solar Financing vs. Other Solar Options
A general comparison of common characteristics. The appropriate structure depends on the borrower's mortgage terms, solar proposal, property, goals, expected ownership period, and overall financial situation.
| Characteristic | FHA Solar Mortgage Structure | Separate Consumer Solar Loan | Solar Lease / PPA |
|---|---|---|---|
| Ownership of the system | Owned by the homeowner | Owned by the homeowner | Owned by the leasing/PPA company |
| Separate monthly solar payment | No separate payment; incorporated into the FHA mortgage payment | Yes, a separate loan payment | Yes, a separate lease or PPA payment |
| Separate financing agreement | No separate financing agreement | Yes, a distinct loan agreement | Yes, a lease or power-purchase agreement |
| Potential lien or UCC considerations | Addressed within the FHA mortgage; subject to program requirements | May involve a separate lien | May involve a UCC filing or similar filing |
| Transfer considerations when selling | Subject to standard mortgage payoff and transfer requirements | Loan balance may need to be paid off or assumed | Lease/PPA may need to be transferred or bought out |
| Integration with the mortgage | Integrated into a single FHA financing structure | Not integrated with the mortgage | Not integrated with the mortgage |
This comparison is general in nature and does not imply that the FHA solar structure is always less expensive or better suited to every borrower.
Work Directly With an Experienced Mortgage Loan Officer
I'm Robert St. John, a mortgage loan officer with Barrett Financial Group. I help homebuyers and homeowners compare mortgage options, understand program requirements, and create a financing plan based on their actual goals — not assumptions or sales pressure.
- Robert St. John — NMLS #1578510
- Barrett Financial Group, L.L.C. — NMLS #181106
- More than 10 years of mortgage-industry experience
- Licensed mortgage loan officer since 2017
- Residential mortgage experience across FHA, conventional, VA, jumbo, Non-QM, construction, investor, and specialty financing
What Clients Say About Working With Robert
"I work at a bank and wasn't able to secure approval through my own institution, but Robert stepped in and made it happen. He was incredibly responsive and stayed on top of every detail throughout the process. It was a real pleasure working with him, and I would definitely recommend his services."
"Working with Robert was one of the best decisions we made during our home buying process. He was transparent, patient, and always available to answer our questions. Communication was consistent. He made this whole process easy and we both learned a lot from him. I can't recommend him enough!"
"Robert and his team helped me with purchasing my house. I was referred to Robert by my realtor. The same evening Robert contacted me and started the process. Very fast and enjoyable working with them. Any questions were answered quickly and professionally. I closed escrow on time."
Verified Google reviews, shared unedited and provided by Robert St. John.
Check Your FHA Solar Eligibility
Six quick questions — about 30 seconds. No credit pull, no obligation.
Common Questions About the FHA Solar Program
What is the FHA Solar Mortgage Program?
Can the program be used to purchase a home?
Can it be used for refinancing?
Is this a cash-out refinance?
How much compensation may be available?
Is the compensation taxable?
Is the compensation a loan?
Is this down-payment assistance?
Does the home need to be my primary residence?
Can I use the program for a second home?
Can I use it for an investment property?
Can the home already have solar?
Will I own the solar system?
Is the solar financed separately?
Are condominiums eligible?
Is an FHA appraisal required?
When is the solar system installed?
How long does installation generally take?
What happens to unused solar escrow funds?
Is approval guaranteed?
Are solar-energy savings guaranteed?
Is the program available in every state?
What credit score is required?
What is an FHA net tangible benefit?
How do I find out whether I qualify?
Find Out Whether the FHA Solar Program Fits Your Plans
Whether you are buying a home or reviewing a possible FHA rate-and-term refinance, the first step is a personalized review of your mortgage, property, solar eligibility, estimated costs, and program requirements.
No obligation. No guaranteed approval. Completing the questionnaire does not authorize a credit inquiry unless separate authorization is provided.